 Skewpoint
 › BTC & ETH option pricer
BTC & ETH option pricer
BTC & ETH option pricer — vanillas, exotics and Greeks on the live vol surface
Price bitcoin and ether options the way a desk does: on a calibrated implied volatility surface, with the smile, not a single flat vol. Vanillas, multi-leg strategies and exotics — barriers, touches, double barriers and digitals — in one crypto option pricer.
Free · instant access · runs in your browser
A crypto option pricer built on the live surface
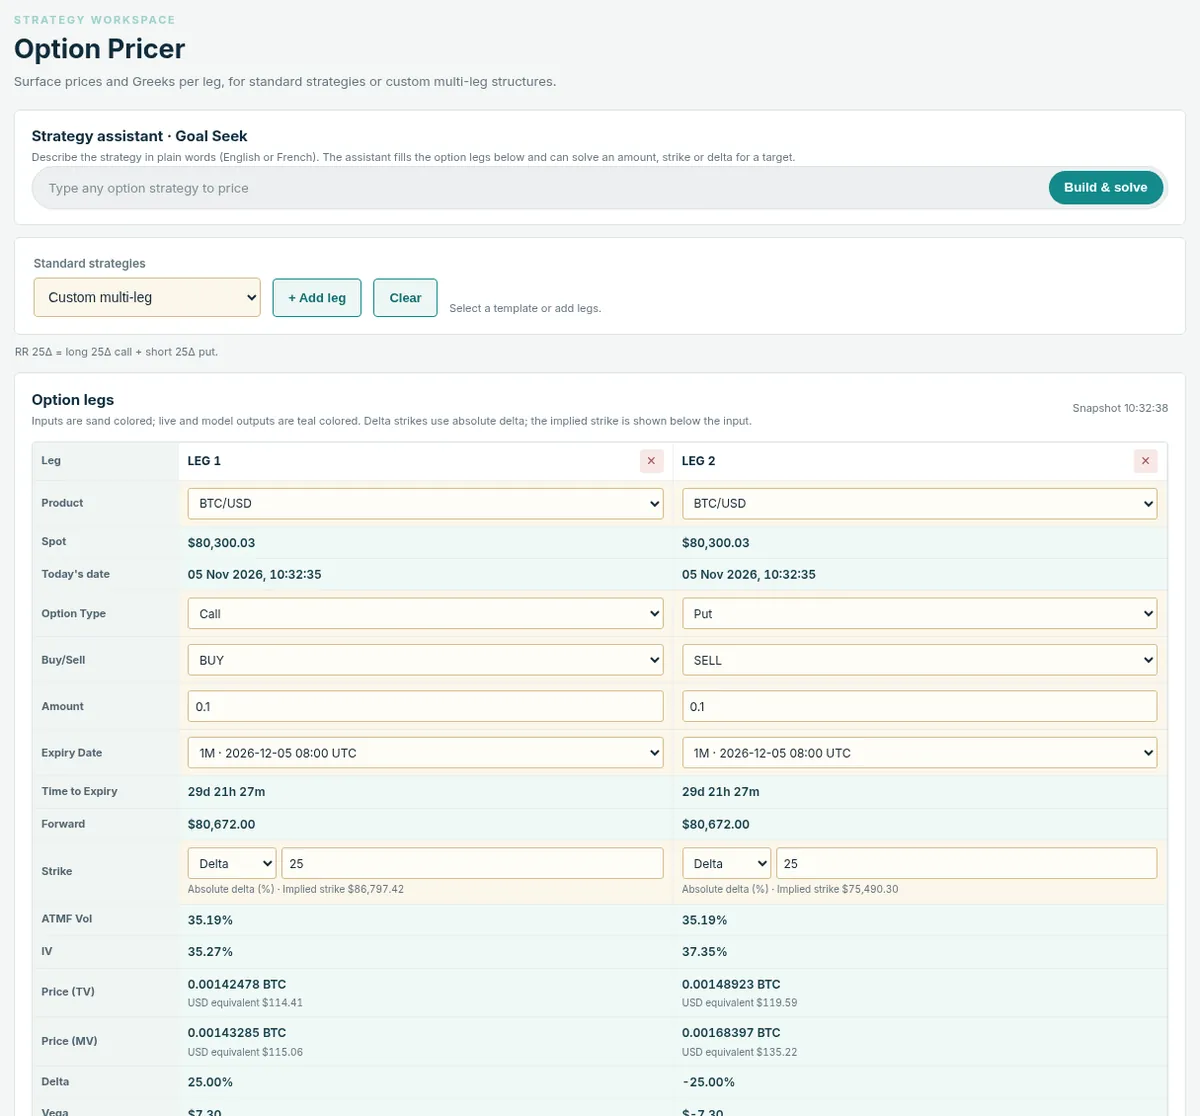
Most online option calculators ask you for a volatility. Skewpoint reads it from the market. Option mid prices for BTC and ETH are turned into implied vols, each listed expiry is fitted with an SVI Jump-Wings curve, and the pricer looks up the vol for your exact strike and maturity on that surface. You choose a listed expiry, a standard tenor (1D to 12M) or any custom date, and enter either a strike or a delta.
Each option leg shows two prices: TV, using the ATMF volatility of the expiry, and MV, using the surface implied vol at the leg’s strike — so you see what the skew is worth. Prices are Black-Scholes on the forward with the chosen vol.
Greeks and strategies
For every leg and for the net position you get Delta, Gamma, Vega, Vanna (dVega/dSpot) and Vomma (dVega/dVol), with BUY/SELL and amount applied, plus the net premium and net transaction delta. Standard packages are one click:
The strategy assistant lets you type a structure in plain English or French — for example “buy a 25-delta BTC risk reversal for March” — and fills the legs for you. It can also goal-seek: solve the amount, strike or delta of one leg to hit a target premium, delta or vega.
Exotic option pricer: barriers, touches and digitals
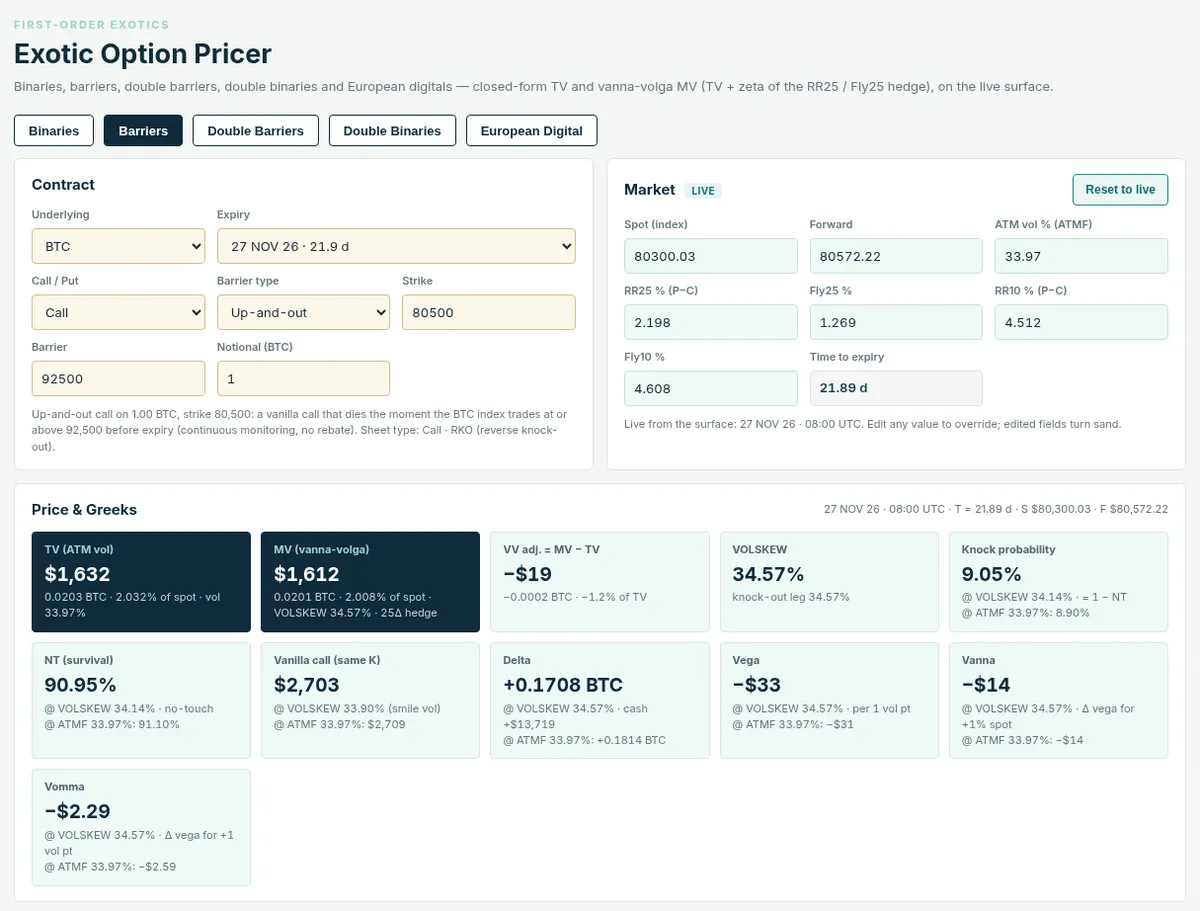
The exotic pricer prices the structures that show up in crypto structured products and OTC books, on BTC or ETH, with USD or coin payouts:
- Barriers — up/down knock-out and knock-in calls and puts, regular and reverse (KO, KI, RKO, RKI).
- Binaries — one-touch paying at hit or at expiry, and no-touch.
- Double barriers — double knock-out and double knock-in.
- Double binaries — double no-touch (DNT) and double one-touch (DOT).
- European digitals — calls and puts paying a fixed amount at expiry.
Each exotic gets a theoretical value (TV) from closed-form formulas at the ATM vol, and a market value (MV) that adds the cost of the smile with a vanna-volga adjustment, using the 25-delta risk reversal and butterfly of the live surface. You also see touch probabilities, the hedge and the Greeks.
Who uses it
Traders checking a quote before they hit it, structurers pricing a barrier or a range note, and anyone who wants to understand how much the BTC or ETH skew is worth in a given structure. The same pricing functions value every trade in the portfolio valuation page and the stress scenarios in risk analysis, so a single option and a whole book are priced consistently. The surface itself is explained on the Bitcoin volatility surface page.
Frequently asked questions
How does Skewpoint price BTC and ETH options?
Vanilla options are priced with Black-Scholes on the forward, using the implied vol read from the live SVI-JW volatility surface at the option’s strike and maturity. Exotics use closed-form formulas for the theoretical value and a vanna-volga adjustment for the market value.
Which Greeks does the option pricer show?
Delta, Gamma, Vega, Vanna (dVega/dSpot) and Vomma (dVega/dVol) per leg and for the net position, along with net premium and net transaction delta. The portfolio page adds one-day Theta.
Can I price a barrier option on bitcoin?
Yes. The exotic pricer handles up and down knock-in and knock-out options (regular and reverse), double knock-in and double knock-out, one-touch, no-touch, double no-touch, double one-touch and European digitals on BTC and ETH.
What is the difference between TV and MV?
TV is the price at the expiry’s ATMF volatility. MV uses the smile: the surface vol at the strike for vanillas, and a vanna-volga adjustment built from the 25-delta risk reversal and butterfly for exotics. The gap between the two is what the skew is worth.
Can I price a custom expiry date?
Yes. Choose a listed expiry, a standard tenor from 1D to 12M, or any custom date; vols are interpolated on the surface.
Is the option pricer free?
Yes. Request access and you are approved instantly.
Try Skewpoint free
Access is free. Request it with your name and email and you are in straight away — no card, no trial clock.