 Skewpoint
 › Crypto volatility today
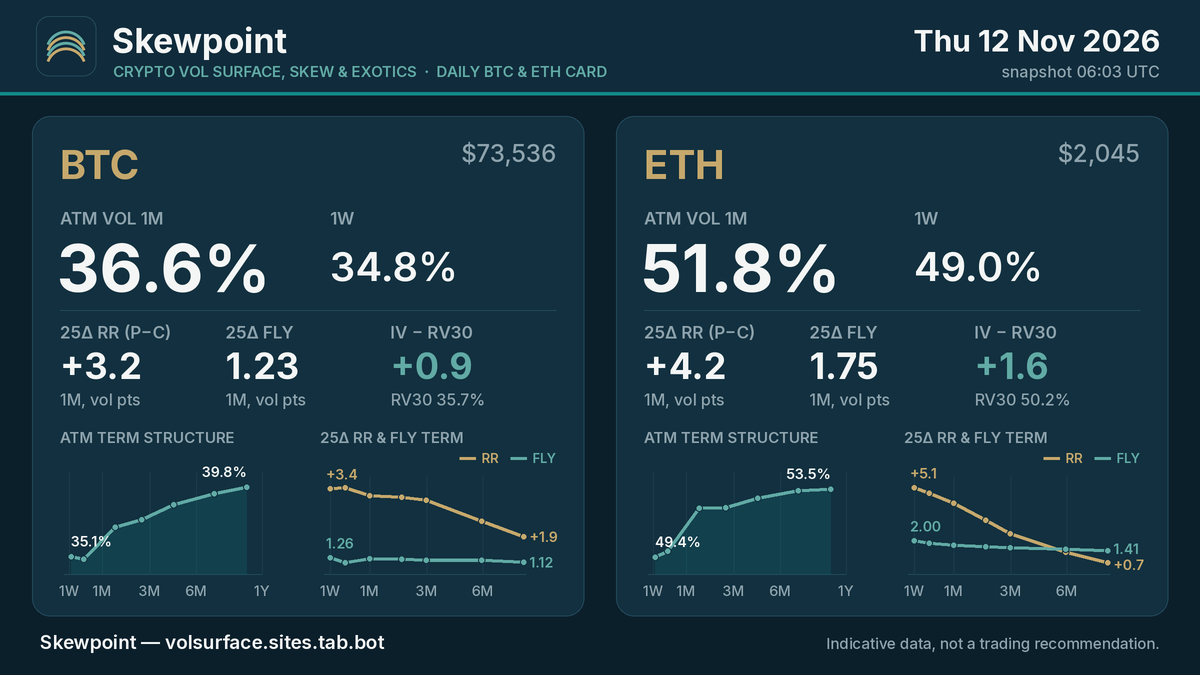
Daily BTC & ETH vol snapshot
Bitcoin & Ether implied volatility today
Today’s 1-month at-the-money implied vol, 25Δ risk reversal, 25Δ butterfly and implied-vs-realised spread for BTC and ETH options, refreshed every morning.
Snapshot of · BTC spot 73,536 USD · ETH spot 2,045 USD
Bitcoin (BTC)
- 1M ATM implied vol
- 36.6%−0.7 vs prev.
- 25Δ risk reversal
- +3.2+0.1 vs prev.
- 25Δ butterfly
- 1.23
- IV − RV
- +0.930-day RV 35.7%
Ether (ETH)
- 1M ATM implied vol
- 51.8%−1.1 vs prev.
- 25Δ risk reversal
- +4.2+0.5 vs prev.
- 25Δ butterfly
- 1.75
- IV − RV
- +1.630-day RV 50.2%
Today’s read
BTC 1-month implied vol is 36.6%, slightly lower than yesterday (0.7 vol points), and puts are still priced over calls (25Δ risk reversal +3.2).
ETH 1-month implied vol is 51.8%, lower than yesterday (1.1 vol points), and puts are still priced over calls (25Δ risk reversal +4.2).
In both coins implied vol sits slightly above 30-day realised vol (BTC +0.9, ETH +1.6 points): options are pricing a little more movement than the market has delivered.
Indicative data, not a trading recommendation. Vols in % (annualised); risk reversal, butterfly and IV−RV in vol points.
Last 11 days
Daily snapshots, newest first. Download the full history as CSV.
| Date | 1M ATM IV | 25Δ RR | 25Δ fly | IV−RV |
|---|---|---|---|---|
| 36.6% | +3.2 | 1.23 | +0.9 | |
| 37.4% | +3.1 | 1.17 | +1.0 | |
| 37.5% | +2.5 | 0.99 | +1.4 | |
| 38.5% | +3.4 | 1.09 | +2.5 | |
| 38.1% | +3.3 | 1.12 | +2.0 | |
| 36.9% | +3.7 | 1.13 | +0.3 | |
| 38.2% | +5.2 | 1.18 | +0.7 | |
| 35.8% | +1.8 | 1.16 | +3.6 | |
| 36.2% | +5.1 | 1.15 | +7.5 | |
| 37.0% | +3.8 | 1.29 | +7.4 | |
| 36.1% | +3.9 | 1.11 | +7.1 |
| Date | 1M ATM IV | 25Δ RR | 25Δ fly | IV−RV |
|---|---|---|---|---|
| 51.8% | +4.2 | 1.75 | +1.6 | |
| 52.9% | +3.7 | 1.90 | +1.7 | |
| 53.1% | +3.1 | 1.61 | +2.8 | |
| 54.3% | +2.6 | 2.01 | +3.9 | |
| 52.8% | +3.5 | 1.73 | +5.1 | |
| 52.1% | +4.0 | 1.67 | +2.8 | |
| 53.3% | +5.6 | 1.96 | +1.8 | |
| 48.8% | +3.3 | 1.60 | +4.9 | |
| 48.5% | +4.5 | 1.31 | +12.1 | |
| 48.2% | +3.2 | 1.29 | +11.4 | |
| 49.3% | +4.9 | 1.54 | +12.3 |
What the numbers mean
1M ATM implied volatility
The implied volatility of a one-month at-the-money option, where at-the-money is the delta-neutral straddle strike. It is interpolated between listed expiries in total variance and quoted annualised, in %. Roughly, it is the size of move the options market prices for the next month: 37% annualised is about 37/√12 ≈ 11% over a month, one standard deviation.
25Δ risk reversal (RR)
The implied vol of the one-month 25-delta put minus the 25-delta call, in vol points. Positive means puts are priced over calls (the market pays more for downside protection); negative means calls are priced over puts (demand for upside). It is the simplest single number for skew.
25Δ butterfly (fly)
The average of the 25-delta put and call vols minus the at-the-money vol, in vol points. It measures how expensive the wings are compared with the middle of the smile: a higher fly means the market prices fatter tails.
IV − RV
One-month implied vol minus 30-day realised vol, in vol points. Realised vol is computed from daily close-to-close log returns at 00:00 UTC, annualised with √365 because crypto trades every day. A positive spread means options are pricing more movement than the market has delivered recently; a negative spread means less.
How it is made
Every morning, live option quotes from a major crypto options venue are fitted with an SVI-JW volatility surface, using the same surface code as the Skewpoint app. The full surface, every tenor from 1D to 12M, 10Δ skew, the smile by strike and the term structure are in the app: see the Bitcoin & Ethereum volatility surface page for what it shows.
See the whole surface, not just one number
Skewpoint has the live BTC and ETH smile, term structure, skew and butterflies for every tenor, an exotic option pricer and portfolio risk. Access is free: request it with your name and email.